Introduction
India has long been a pioneer in the realm of digital payments, with the Unified Payments Interface (UPI) emerging as a cornerstone of this innovation. This fast-growing payment mechanism, which allows users to transfer money instantly via mobile applications, has been celebrated for its convenience and accessibility. However, a recent announcement by the National Payments Corporation of India (NPCI) signals the end of an era. Starting next month, UPI will introduce a fee for certain transactions, a decision that has sparked intense debate among consumers and industry experts alike.
The fee structure aims to generate revenue that could be reinvested into the system and its infrastructure, yet it raises the question: who truly benefits from this change? Critics argue that this move could undermine the very principles of accessibility and ease that have driven UPI's widespread adoption. The announcement has led to concerns about whether the new charges will dissuade users from relying on this digital payment method.
The UPI Landscape
Launched in 2016, UPI has revolutionized the way Indians conduct transactions. The system allows users to send or receive money in real-time, making it an attractive option for both consumers and merchants. As of 2022, UPI transactions surpassed a staggering 50 billion annually, reflecting its deep integration into the daily lives of Indians. The current fee, which applies primarily to commercial transactions above a certain threshold, is seen as a shift from the previous model that was built on the premise of no transaction costs for users.

Supporters of the fee argue that it is necessary to sustain and enhance the UPI system. By imposing a nominal charge, the NPCI can ensure that infrastructure develops to meet the growing demands of digital commerce. However, many consumers are apprehensive about the implications of additional costs, especially in a country where economic disparities persist.
Rising Concerns in the Digital Sphere
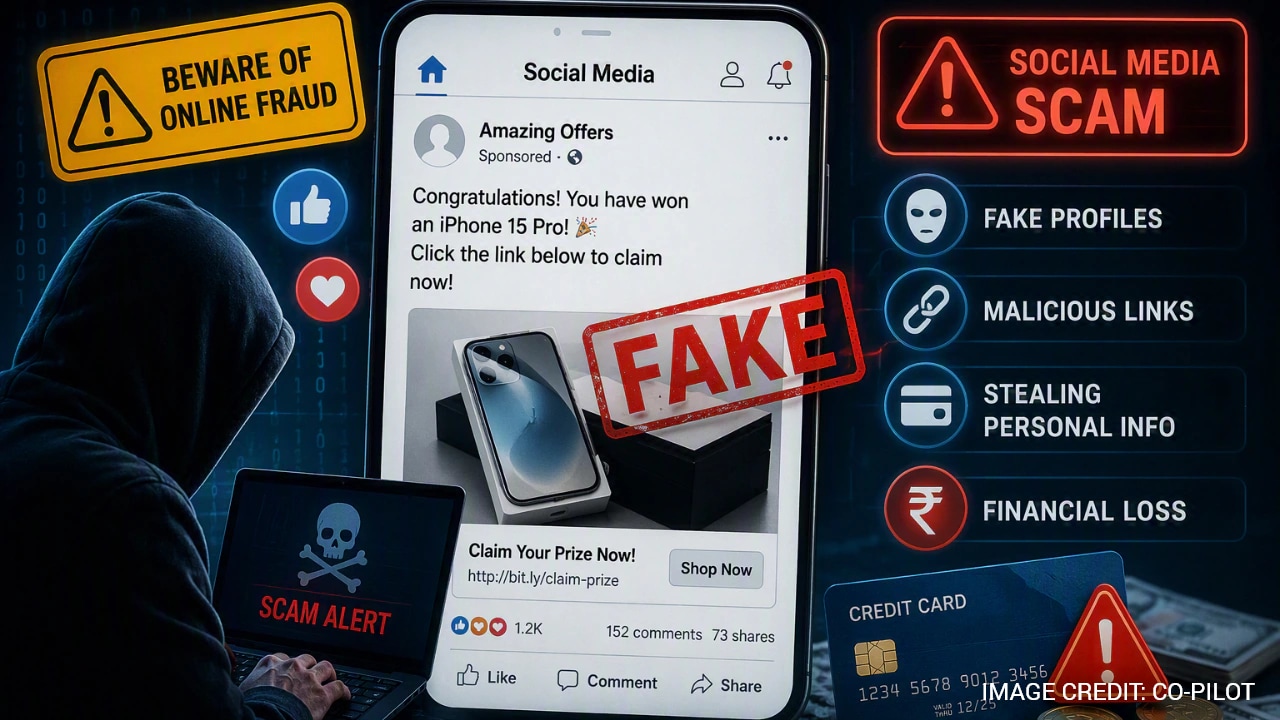
Compounding the concerns surrounding UPI's new fee is the alarming rise in online scams targeting unsuspecting individuals. Recent cases reported in Mumbai highlight the vulnerability of users in the digital payment ecosystem. Three residents collectively lost over ₹7 lakh in online scams linked to social media platforms like Facebook and Instagram. These incidents showcase how the ease of digital transactions can be exploited by fraudsters, leaving victims to grapple with significant financial losses.
As the digital landscape evolves, the need for robust security measures becomes paramount. The government and relevant authorities have been urged to enhance cybersecurity frameworks to protect consumers. Educating users about potential scams and fraud tactics is equally crucial, as awareness plays a critical role in preventing such incidents. The juxtaposition of a fee-laden payment system and rising fraud amplifies the challenges that India faces in fostering a secure digital environment.
The Human Element
In a separate yet poignant incident, an Indian man tragically died on a Malaysia Airlines flight to Sydney after suffering an asthma attack. This event serves as a reminder of the unpredictability of life and the importance of health, but it also underscores the need for effective emergency protocols in the travel and airline sectors. The aftermath of such incidents often leads to discussions about preparedness, training, and the capacity of airline staff to respond to medical emergencies.
While the deaths of individuals can often seem distant from discussions of digital payments, the underlying themes of safety and security resonate across both narratives. Whether it is safeguarding financial transactions or ensuring passenger health, the call for vigilance remains constant.

Moving Forward
As India navigates these turbulent waters, stakeholders must engage in dialogue about the future of digital payments. Policymakers, financial institutions, and consumers need to collaborate to forge a path that balances innovation with the protection of users. With UPI's new fee structure, India finds itself at a critical juncture: will the benefits of improved infrastructure outweigh the potential deterrents posed by transaction fees?
In the coming months, it will be essential to monitor user sentiment towards UPI as the fees come into effect. Will consumers adapt, or will they gravitate towards alternative payment methods? As digital finance evolves, India must also reflect on the lessons learned from both the ongoing digital payment discourse and the troubling rise in online scams.
Conclusion
The introduction of fees for UPI payments presents a complex challenge for India's digital finance ecosystem. With the benefits of improved infrastructure on one side and potential consumer pushback on the other, the coming months will be pivotal. The need for increased security against online scams further complicates the landscape, emphasizing that both financial and personal safety must be prioritized. As India continues to champion digital innovation, the balance between access, security, and cost will define its path forward.
For more on India's evolving economic landscape, read Rising Sugar Prices in India Disrupt Festive Celebrations and Amazon Expands Alexa+ in India Amid Digital Payment Debate.